
Skip to content
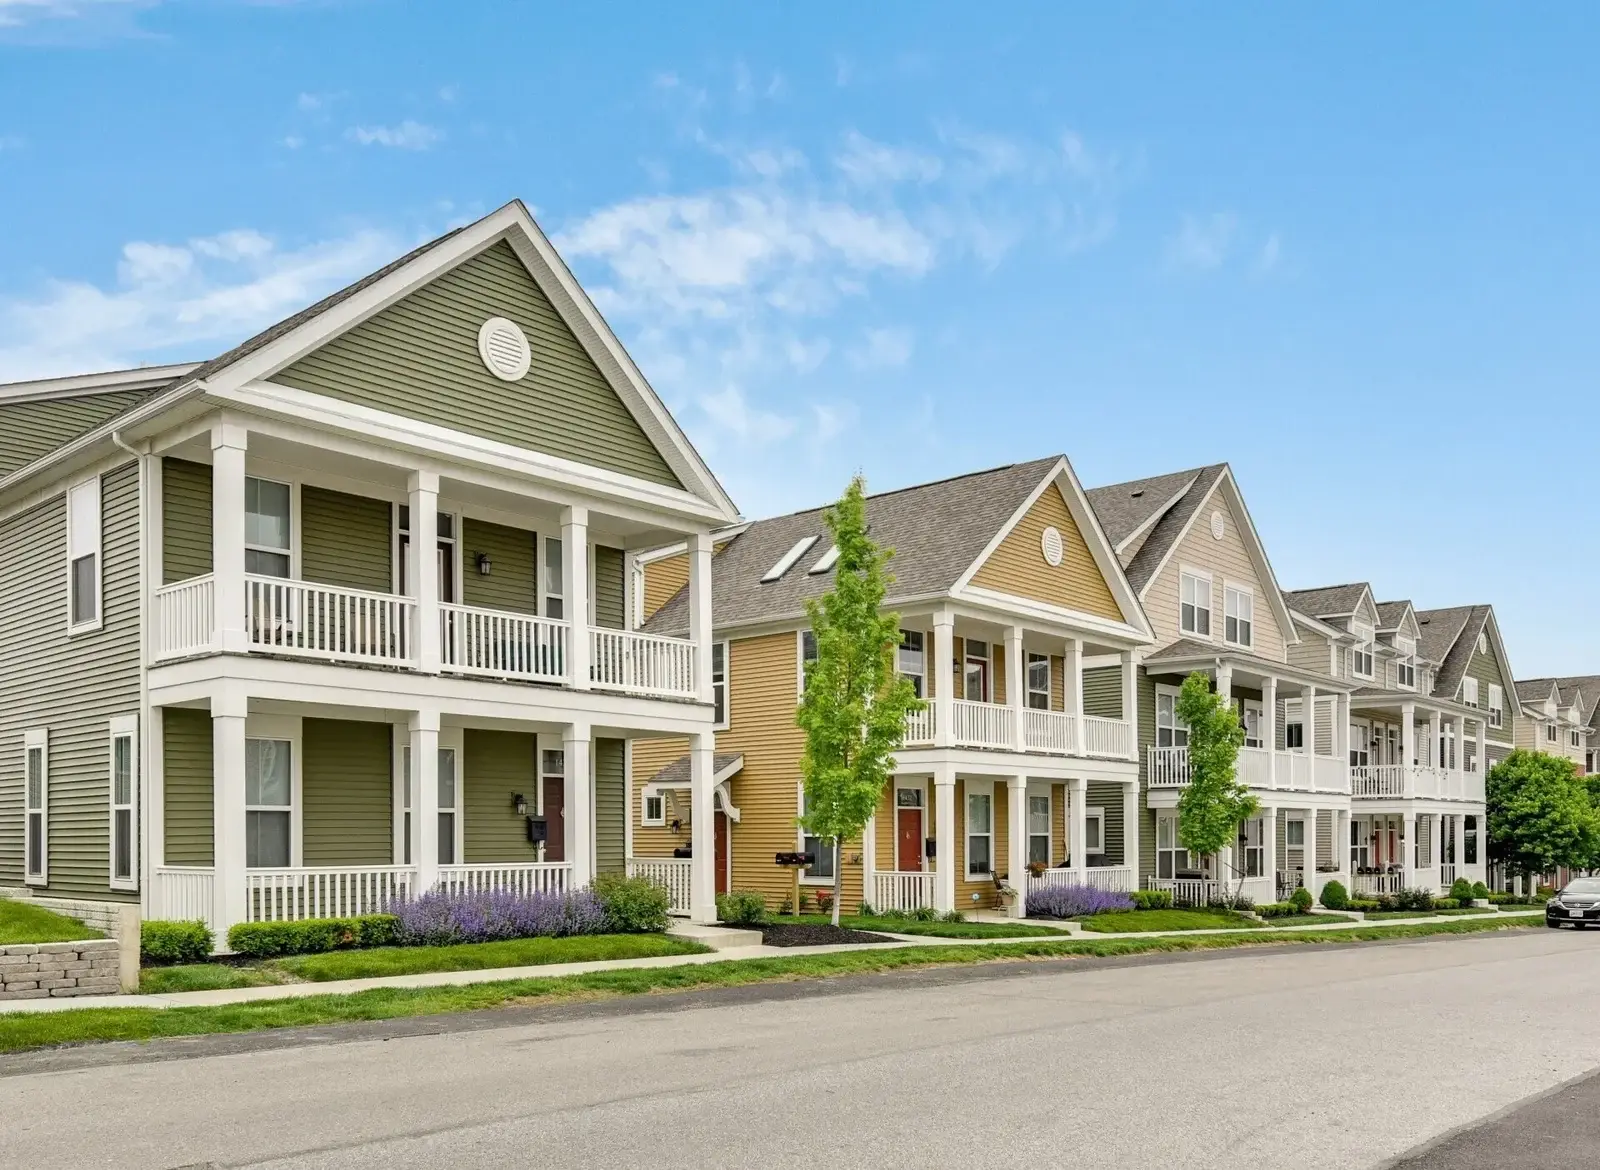
Grandview Village, a Metropolitan Holdings apartment community in Columbus, Ohio.

Partner FAQ

Partner FAQ

What a private real estate position is, who can hold one, how the money moves, and what arrives at tax time.

These are the questions investor relations is asked most often. Where an answer depends on the terms of a specific fund, the terms are the ones published in that fund’s offering documents, and those documents govern.

The firm and what you would own

Who is Metropolitan Holdings?

A multifamily developer founded in Columbus in 1998. The firm designs, builds, manages, and invests in its own apartment communities across Ohio, and has developed more than $800M of multifamily assets since founding — a measure of development volume, not of investor return. You can see what that has produced on the communities map.

The distinction that matters when you are comparing sponsors is that the same firm does the developing, the general contracting, and the property management. What vertical integration changes for an investor is worth reading before you compare us with a sponsor who subcontracts all three.

What am I actually buying?

An interest in a fund that puts capital into ground-up apartment development. Not shares in a company, and not an existing occupied building bought at a market price — capital goes in before there is a building, and the outcome depends on completing construction near budget, leasing the property up, and reaching a capital event.

That is a different instrument from a listed REIT, and a different risk profile from buying stabilised property. Both comparisons are worked through in private real estate versus REITs and in the guide to Ohio multifamily investing.

How do you decide a community is worth building?

The pro forma uses untrended rents. A community is tested against what its submarket rents for today, not against a rent-growth curve that has to arrive for the numbers to work, and the other assumptions are set at market rather than at the top of the range.

Rents at our communities are then set at or below market. If a deal does not make sense at today’s rents, it is not good enough for us to build.

The reason this is worth asking any sponsor: a building underwritten to a rent its submarket already supports can be checked against leases signed down the street. One underwritten to a rent that has to arrive later cannot be checked at all. Why a developer builds where it does goes into how a submarket is judged.

Do I lend to the communities or own a share of them?

Either — they are two separate funds and two different positions. A debt fund lends to the projects and is paid interest; it sits ahead of the equity, and its return is capped at the interest rate. An equity fund owns a share of the projects; it is paid after the lenders, its return is not capped, and it carries the downside.

Neither is better. They price different risks. The two are set side by side, line by line, on the fund terms page, and the reasoning behind the choice is in debt fund versus equity fund.

Who can invest

Who is eligible?

Accredited investors only, as defined under Rule 501 of Regulation D. The two most common ways to qualify are a net worth over $1,000,000 excluding your primary residence, or an annual income above $200,000 individually — $300,000 jointly — for the past two years. Those are not the only routes; Rule 501 also recognises certain entities and certain professional credentials.

Accredited status has to be confirmed before a subscription is accepted, and confirming it is a step in the process rather than a box you tick. Investor relations will tell you what is needed for your situation.

What is the minimum investment?

$100,000 in both funds. Commitment size also sets which preferred-return tier applies, so the minimum is not only an entry threshold — see how the preferred return works below.

Committing and funding

What happens after I commit?

You sign a subscription agreement. Funding your commitment typically happens within two to six months of signing rather than immediately, so a commitment and a wire are two separate moments. Once your capital is contributed, it is deployed into a community within about thirty days, and your preferred return begins accruing on the date of deployment.

The full sequence, from first conversation to a funded position, is in how to invest in a private real estate fund.

What is a preferred return, and when does it start?

A preferred return is the first claim on profits: investors are paid up to that rate before the sponsor shares in anything. In the equity fund it is banded by commitment size, from 8% at the minimum to 10% at the largest tier. It is a target and a priority, not a promise of payment — it is paid from what the projects actually produce.

It begins accruing on the date your capital is deployed, not the date you signed. And it accrues: it is not paid out currently, but builds until a capital event occurs. That distinction is the one most often misread, and it is worked through in what a preferred return is, and what it is not.

What fees do I pay?

None are deducted from your investment. Fees are charged at the community level, which means your contributed capital goes in whole and the fees come out of total returns before distributions to partners are calculated.

That is a real structural difference from a fund that takes a load off the top, and it is also not the same as a deal with no fees — the fees are still paid, just from a different place in the order. Fees in a private real estate deal, line by line sets out where each one sits.

Can I reinvest my distributions?

Not within the same fund — the funds do not offer reinvestment. If there is a new offering open at the time you receive a distribution, you may commit those proceeds to it, but that is a fresh subscription rather than an automatic election.

Getting money back

How long is my money tied up?

The equity fund targets a three to twelve year hold per project, with return of original capital targeted in three to five years. The debt fund targets three years, extendable to five. Both are targets drawn from the offering documents rather than commitments, and a project that takes longer to build or lease takes longer to reach the event that returns capital.

What a targeted hold period actually commits you to is the longer answer.

Can I sell my interest early?

Treat it as no. These interests are illiquid, they are not registered, and there is no public market for them. Plan on holding to the end of the term rather than on finding a buyer, and do not commit money you may need before then.

Why would you sell a community rather than refinance it?

Both are capital events, and the choice is made on what the market will support at the time.

  • Sale when market pricing is meaningfully higher than what a refinance would support. It realises the gain and returns capital while the property is at peak appeal.
  • Refinance and hold when the refinancing proceeds can return all accrued preferred return and at least half of original capital. That keeps ownership, ongoing cash flow, and the depreciation that comes with continuing to hold the asset.

The two paths produce different after-tax outcomes for the same community, which is what the after-tax return calculator exists to show. When development capital comes back covers the sequence.

How are distributions handled?

You are kept in the loop through the transaction, and the details of a distribution are provided before it is made rather than after. Distributions are typically sent to your chosen method within about thirty days of the capital event.

Tax

What do I receive at tax time?

A Schedule K-1 (Form 1065) each year, reporting your share of the fund’s income, depreciation, and deductions. The fund is a partnership for tax purposes, so it does not pay tax itself — the items are allocated to you and land on your own return.

Why does my K-1 show a loss when the building is full?

Because depreciation is a deduction that corresponds to no payment, and a newly built property generates a great deal of it early — particularly once a cost segregation study separates the shorter-lived components from the building itself. A community can be leasing well, covering its debt service, and still report a loss.

Why new development produces large paper losses works through the mechanism.

Can I use that loss against my salary?

Usually not. Losses from a passive activity can offset passive income, and for most investors a fund interest is passive. They cannot offset wages, salary, interest, dividends, or gains on stock. A loss you cannot use is suspended and carried forward rather than lost, and it becomes usable against passive income later or on a fully taxable disposition.

Whether that makes a position worth more or less to you depends entirely on your own income, which is what the after-tax return calculator models. The narrow exceptions are covered in can real estate losses offset W-2 income. This is general information; your CPA has to answer it for your return.

Can I invest through a self-directed IRA?

It is a route some investors use, and it changes the arithmetic rather than simply relocating it. Inside a retirement account there is no current tax for a depreciation deduction to reduce, so the tax benefit that makes a development position attractive outside an account does nothing inside one — and a leveraged property can raise questions about unrelated business taxable income.

Private real estate in a self-directed IRA sets out the trade. Which custodians and account types can be accommodated is a question for investor relations.

Risk and reporting

What are the risks?

Real estate development involves substantial risk, including construction delay and cost overrun, lease-up risk, interest-rate and refinancing risk, illiquidity, leverage, and loss of principal. Interests in private offerings are not registered, are not freely transferable, and there is no public market for them. You may lose some or all of your capital.

The specific ways a development deal goes wrong, and what each one does to an investor’s position, are set out in what happens when a development deal goes wrong.

What will I hear from you, and how often?

Monthly statements and quarterly updates on the communities, through the partner portal and by email, including construction photos and progress metrics as a community moves through building and lease-up.

Who do I talk to?

Investor relations, directly. You can send us a question or reach the team through our contact page. Existing partners can reach their statements and documents through the partner portal.

Still have a question

Investor relations answers these directly, and there is no obligation attached to asking one.

This page is general information, not investment, tax, or legal advice, and not an offer to sell or a solicitation of an offer to buy any security. Any offering is made only through the relevant fund’s offering documents, to accredited investors, and those documents govern in the event of any inconsistency with this page.

Targeted returns, preferred returns, and hold periods are targets drawn from the offering documents. They are not a guarantee, they do not predict results, and no specific return is promised. Private real estate is illiquid and speculative, and investors may lose some or all of their capital.

Tax outcomes depend on facts specific to each investor, and tax law changes. Nothing here is advice about your situation — consult your own CPA and counsel.

Get what we send partners

How development deals are structured, what we are seeing in Ohio submarkets, and what we are building. No offering material.

We use your address to send the newsletter and nothing else. Subscribing is not an application to invest and does not make you a client.